
UCO Bank benchmark rates have been revised recently, while the MCLR remains unchanged. This decision impacts various loan products offered by the bank.
Overview of UCO Bank’s Recent Rate Changes
UCO Bank has recently made notable adjustments to its benchmark rates, reflecting its commitment to providing competitive financial products. The latest revisions are aimed at enhancing customer experience while maintaining stability in the banking sector.
Among the changes, UCO Bank has altered various benchmark rates, including the UCO Bank benchmark rates for loans and deposits. These adjustments are designed to align with current market trends and customer needs, ensuring that the bank remains a viable choice for borrowers and savers alike.
Despite the shifts in other rates, UCO Bank has chosen to keep its Marginal Cost of Funds Based Lending Rate (MCLR) unchanged. This decision signifies the bank’s intent to offer consistent lending rates, which can be reassuring for customers planning their financial commitments.
Key highlights of the recent rate changes include:
- Increased rates for specific fixed deposit schemes.
- Revised interest rates on savings accounts.
- Adjustments to home loan rates based on the revised benchmarks.
These modifications are a part of UCO Bank’s ongoing strategy to adapt to the evolving economic landscape while ensuring that customers have access to reliable and competitive financial solutions.
Impact of MCLR Stability on Borrowers
The stability of UCO Bank’s benchmark rates, particularly its Marginal Cost of Funds based Lending Rate (MCLR), has significant implications for borrowers. By maintaining the MCLR unchanged, UCO Bank has provided a sense of predictability that is crucial for individuals and businesses alike.
When benchmark rates remain stable, borrowers can plan their finances more effectively. This consistency enables loan seekers to make informed decisions regarding:
- Home Loans: With the MCLR steady, borrowers can expect their EMIs to remain consistent, easing the burden of financial planning.
- Business Loans: Entrepreneurs can confidently invest in expansion and operations without the fear of fluctuating interest rates affecting their cash flow.
- Personal Loans: Consumers can anticipate manageable repayments, allowing them to budget for other essential expenses.
Moreover, the unchanged MCLR reflects UCO Bank’s commitment to providing a stable lending environment, reinforcing trust among its customers. As the bank continues to navigate the complexities of the financial market, the focus on maintaining benchmark rates will be a vital factor in supporting borrowers’ needs and fostering economic growth.
UCO Bank benchmark rates Explained
The UCO Bank benchmark rates serve as a crucial indicator for both borrowers and depositors, shaping the financial landscape for many customers. These rates help determine the interest on loans and deposits, influencing overall lending and saving behaviors.
Recently, UCO Bank has made notable adjustments to certain benchmark rates, while maintaining the Marginal Cost of Funds based Lending Rate (MCLR) at its current levels. This decision reflects the bank’s commitment to providing stability in a fluctuating economic environment.
Understanding the UCO Bank benchmark rates is essential for consumers looking to navigate their financial options effectively. The key components include:
- Base Rate: This is the minimum rate at which UCO Bank lends to its most creditworthy customers.
- Benchmark Prime Lending Rate (BPLR): Used to determine the interest rates on various loans, impacting the cost of borrowing.
- Fixed Deposit Rates: Influencing returns for savers, these rates are vital for customers looking to invest their funds securely.
In summary, the recent revisions in benchmark rates highlight UCO Bank’s responsiveness while ensuring that customers can rely on the existing MCLR for their borrowing needs.
Customer Reactions to the New Rates
As UCO Bank announces its revised benchmark rates, customer reactions have been mixed, reflecting a blend of optimism and concern. Many borrowers have expressed relief that the MCLR has remained unchanged, believing that this stability will provide them with predictable repayment terms.
Positive feedback has come from customers who appreciate the bank’s effort to maintain competitive rates while offering clarity on changes. Some customers mentioned:
- “I am happy that UCO Bank’s benchmark rates are still favorable for my home loan.”
- “The stability in MCLR means I can plan my finances better without worrying about sudden hikes.”
However, not all responses have been favorable. A segment of customers voiced concerns regarding the adjustments made to specific benchmark rates, stating that these changes could impact their existing loan agreements negatively. One customer noted:
- “While the MCLR is stable, the new benchmark rates might affect my savings account interest.”
In conclusion, while UCO Bank benchmark rates have brought some relief, the overall customer sentiment remains cautious as they navigate the implications of these changes on their financial commitments.
Future Outlook for UCO Bank’s Interest Rates
The future outlook for UCO Bank’s interest rates remains a topic of keen interest among both borrowers and investors. As the bank has recently revised select benchmark rates while maintaining its Marginal Cost of Funds-Based Lending Rate (MCLR), the implications for the market could be significant.
Market analysts suggest that UCO Bank’s decision to keep the MCLR unchanged indicates a commitment to providing stability in an otherwise fluctuating economic environment. This stability may attract more customers looking for reliable lending options.
Factors influencing future rates include:
- Inflation Trends: Should inflation remain high, UCO Bank may need to adjust its benchmark rates to maintain its profit margins.
- Regulatory Changes: Any modifications in banking regulations could prompt UCO Bank to reassess its interest rate strategies.
- Market Competition: Increased competition from other financial institutions may push UCO Bank to offer more attractive rates to retain customers.
In conclusion, while UCO Bank benchmark rates have seen some adjustments, the overall landscape suggests a cautious but optimistic approach moving forward. Stakeholders will be closely monitoring these developments as they may shape the bank’s future direction.
Recent adjustments in UCO Bank benchmark rates have sparked discussions among financial analysts regarding their impact on lending practices. As the market evolves, UCO Bank benchmark rates continue to demonstrate proven stability, reassuring customers and investors alike.
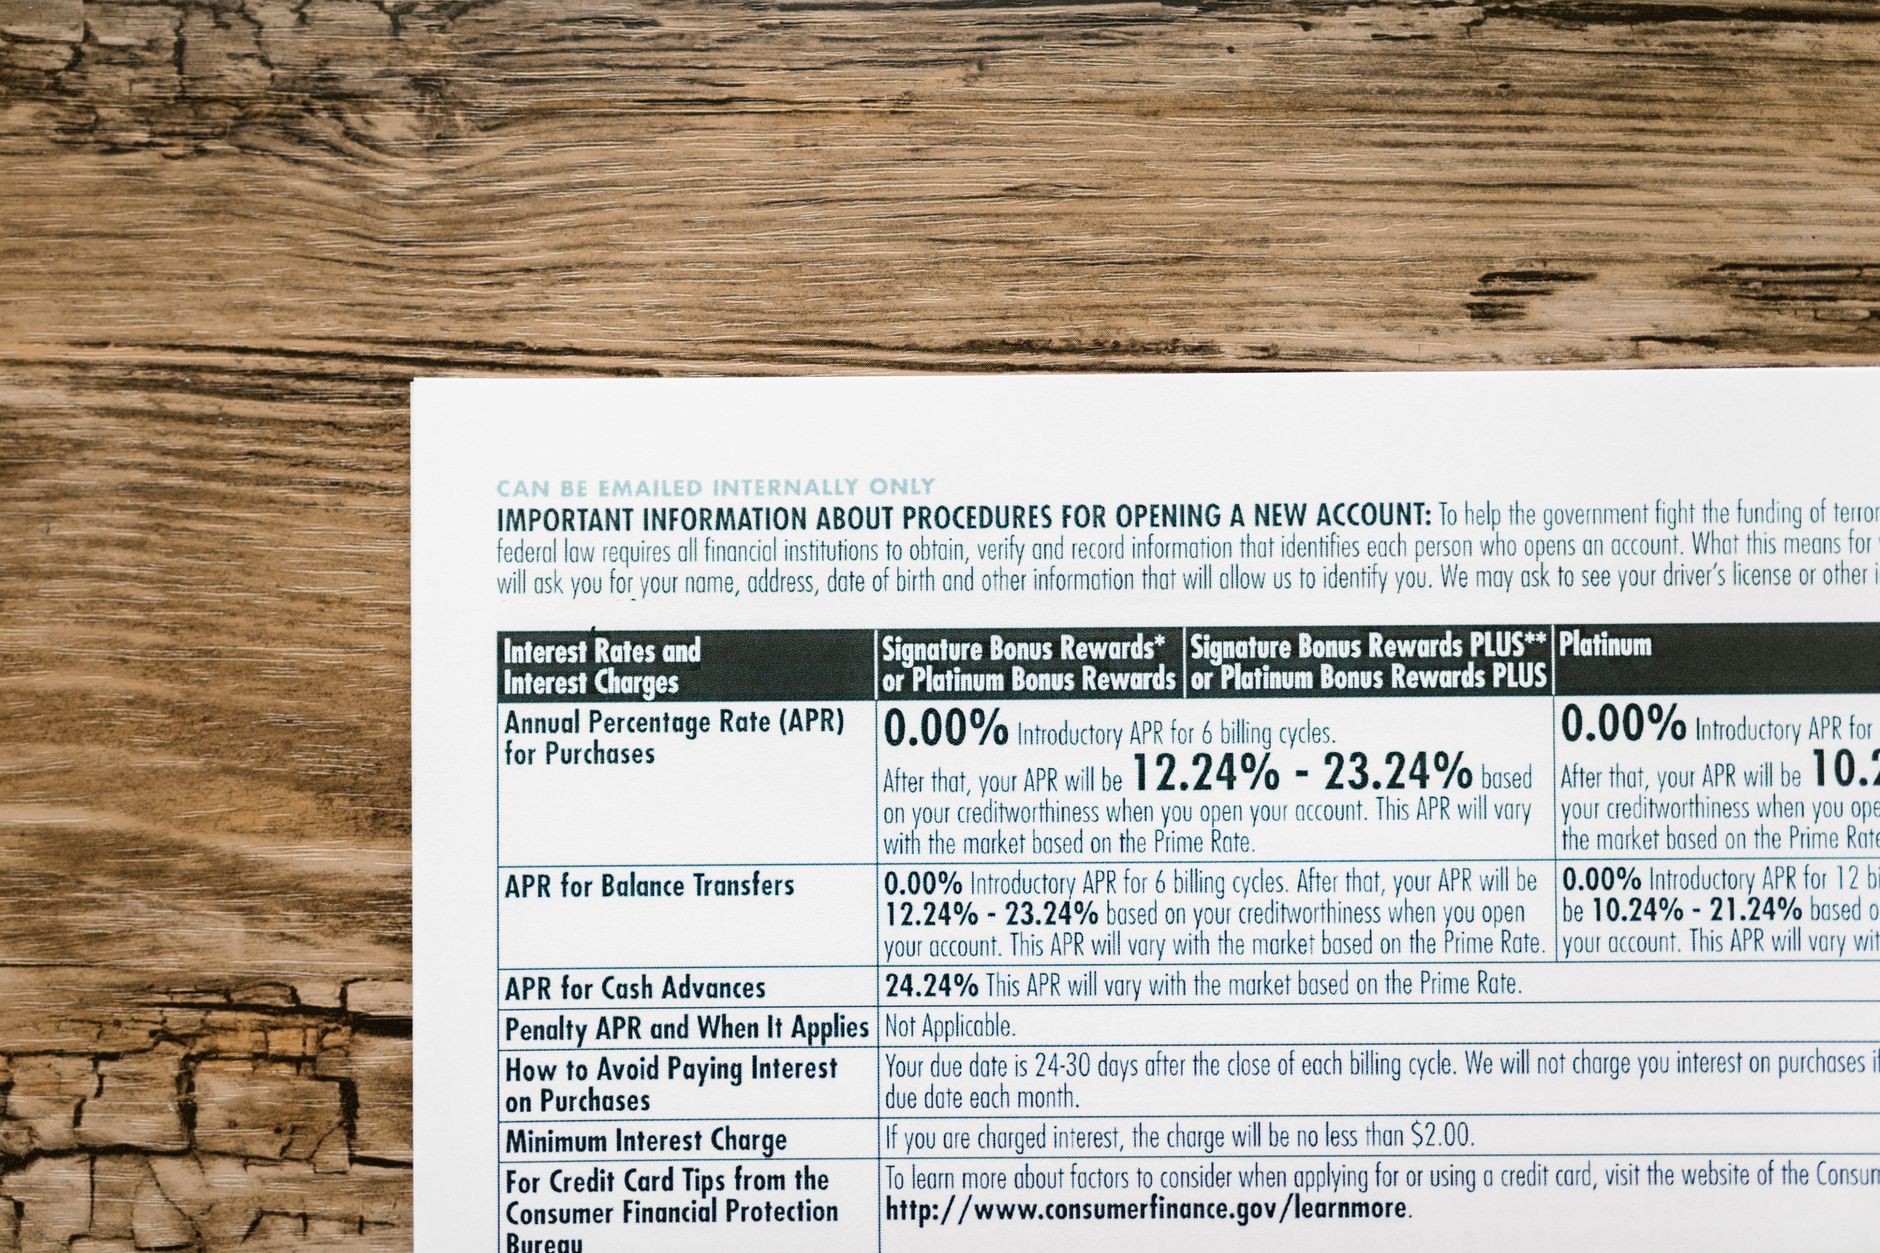
Photo by RDNE Stock project on Pexels
Read the original
You might also like
- Stocks Above 200 DMAs: What Are the Best Proven Picks?
- XRP ETF inflows: Proven Demand Surges to $1.68 Billion
- Corporate actions this week: Clear insights on key updates